Do I need to attach IBKR reports to GPM311?
You enter the declaration data in section H of GPM311. Keep the IBKR reports and bank statements that support the amounts, dates and foreign tax withheld, so you can provide them if VMI asks.
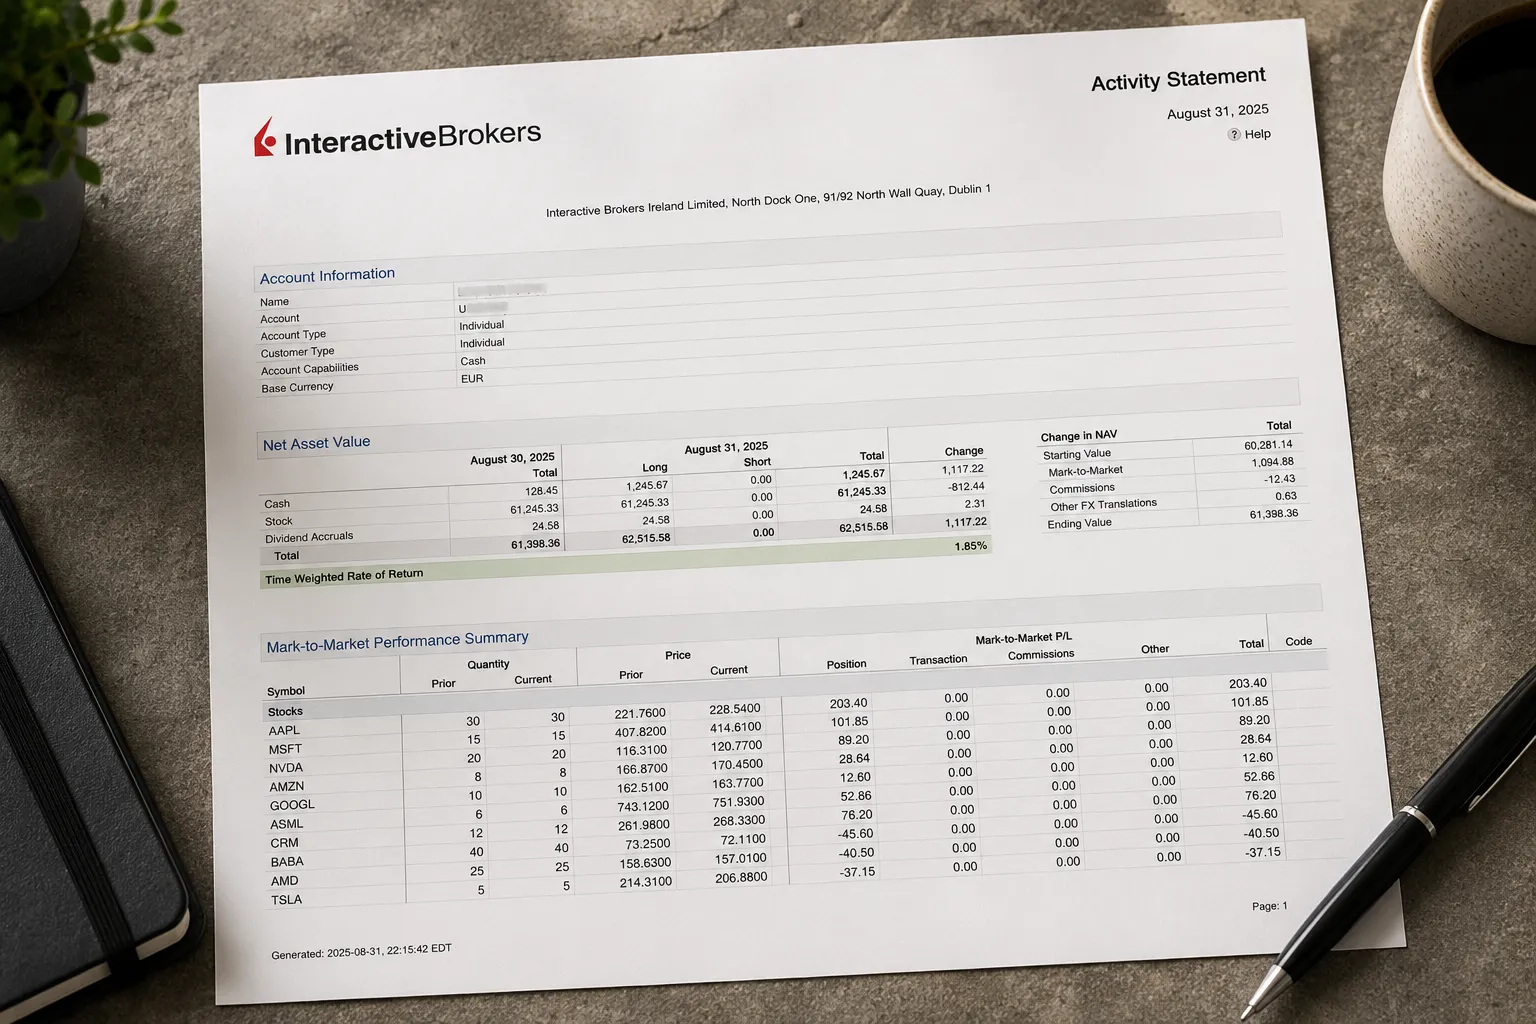
You can declare an IBKR account as an investment account if you use it under the rules of Lithuania's investment account tax regime. VMI guidance includes an Interactive Brokers Ireland Limited account example and explains that a person investing through a brokerage may declare the personal cash account shown in that brokerage account. If you already use a suitable IBKR account for investing, you do not need to create a separate "IBKR investment account". You declare the existing account to VMI.
Supported sources: IBKR Activity Statement and Dividend Report. Rules checked against VMI and Interactive Brokers information.
The IBKR account is declared in section H of GPM311. This section records the account details and the transactions needed to calculate tax. The regime applies only to eligible financial products.
GPMas needs the annual Activity Statement CSV. If it contains dividend activity, also provide the Dividend Report CSV. If that report is unavailable, GPMas supports an explicit review of dividend countries and classifications using supporting documents. The separate IBKR report guide shows how to download the files.
GPMas does not file the return for you or send data to VMI. It extracts account details, GPM311 transaction rows, dividend information, source comparisons and warnings from the uploaded files. The files are not stored after the request. The GPMas methodology page explains the calculations.
VMI asks for the country, the financial institution or service provider name and code, the account number or unique account identifier, the opening date and the date from which you use the account under the investment account regime. Check these details in your IBKR account, agreements and official reports.
| Field | What to enter | Where to check |
|---|---|---|
| Financial institution | The official name of the IBKR legal entity that serves your account. | Your IBKR agreement, account documents or report header. |
| Institution code | The registration code of the IBKR legal entity that serves your account. | Your IBKR agreement or other official account documents. |
| Account identifier | Your IBKR Account ID, which usually starts with U. | Client Portal and the "Account Information" section of an Activity Statement. |
| Country | The country of your IBKR legal entity, not the exchange or the company whose shares you bought. | Your IBKR agreement and official account documents. |
| Opening date | The date on which the account was opened. | Your account documents. Contact IBKR Client Services if you cannot find it. |
| Regime start date | The date from which you actually use this account under the investment account regime. | The date must match the way you used the account and the transitional rules. |
Tax on returns from eligible investments is deferred while the amount paid out of the investment account does not exceed the contributions accumulated by that date. The order of transactions therefore matters. Annual contribution and withdrawal totals alone are not enough.
A transfer from a regular bank account to IBKR increases your contribution balance. Cash held in the account on the regime start date is also treated as a contribution. A transfer from IBKR to a non-investment account, or using the money for a non-investment purpose, reduces the balance. The part of a withdrawal that exceeds the contribution balance is treated as taxable income.
A transfer between two investment accounts declared by the same person is not a new contribution or withdrawal and has no tax consequence. A transaction in a foreign currency must be converted at the official rate for that date. For example, several USD contributions are converted separately using the rate for each contribution date, not one year-end rate. This rule appears in the instructions for GPM311 section H.
Buying or selling an eligible financial product does not normally create a personal income tax liability at the time of sale while the money remains under the investment account regime. Section H is not limited to contributions and withdrawals. It also contains other information needed to calculate tax. Dividends, interest, ineligible financial products and money used outside the permitted investment purposes follow their own rules. The VMI description of GPM311 explains what each part of the return covers.
Suppose you transfer EUR 5,000 to IBKR in January 2026, another EUR 2,000 in March, withdraw EUR 1,500 in June and contribute EUR 1,000 in September. Before the June withdrawal, the contribution balance is EUR 7,000, so the EUR 1,500 withdrawal does not exceed it. The contribution balance after all four transactions is EUR 6,500.
If you had withdrawn EUR 8,000 in June, the withdrawal would have exceeded the contribution balance at that time by EUR 1,000. The September contribution would not reverse the earlier excess. A real return may also involve several accounts, currencies, dividends and other transactions.
Dividend reporting depends on the source country, gross amount and any foreign tax withheld. The net amount actually credited to your IBKR account increases the investment account contribution balance.
GPMas reads dated dividend and withholding cash events from the annual Activity Statement. It uses the Dividend Report to check payer countries and classifications and compare grouped gross dividend and withholding totals. The two reports do not need matching rows for every payment.
For non-EUR dividends and withholding, GPMas converts each Activity Statement cash event using the exchange rate for its own date. A broker-reported EUR total does not replace these dated conversions.
GPMas uses these CSV files for the annual summary:
The IBKR CSV guide shows how to download the reports. IBKR lists their publication dates in its annual reporting calendar.
You enter the declaration data in section H of GPM311. Keep the IBKR reports and bank statements that support the amounts, dates and foreign tax withheld, so you can provide them if VMI asks.
Declare each investment account that you actually used under the regime. Transfers between your own declared investment accounts do not create a tax consequence and are not reported in GPM311 as contributions or withdrawals.
Check your old and current IBKR agreements and statements for the legal entity, country, account identifier and migration date. Keep documents for both periods. If it is unclear whether VMI expects one account or two for your migration, ask VMI about your specific case.
A joint account and transfers between spouses depend on account ownership and the spouses' property regime. VMI states that a transfer between declared investment accounts of spouses is not treated as a withdrawal when both spouses use the regime and their property is held under the community property regime. The exception does not apply when a marriage agreement establishes a different property regime.
For joint accounts or transfers between spouses, read the VMI guidance for spouses.